How Banks Can Monetize Embedded Lending


In recent years, the financial services industry has seen a new offering in the form of embedded lending . Customer expectations have changed, and many small business owners today prefer faster, easier access to credit. Many are also turning to digital tools and processes to run their businesses, whether for accounting software, invoicing, or e-commerce. These entrepreneurs usually find it more convenient to access financial products, including small business loans, on the digital platforms where they already spend so much of their time. This shift has created a significant opportunity for regional and community banks to capitalize on the embedded lending trend . Partnering with Banking as a Service (BaaS) platforms allows banks to reach more small business borrowers without the high cost of direct marketing or building new tools from scratch. This article explains how your bank can build and offer plug-and-play lending APIs. You’ll learn about the technical setup, compliance steps, and how to work with platforms that already serve small businesses. If your bank is looking for a new way to grow its business lending division, embedded lending is worth exploring.
Embedded Finance and Banking as a Service Explained
Embedded finance is rapidly gaining traction in the financial services industry. Global Market Insights, for example, estimates that the market for embedded finance will grow from $105.8 billion in 2024 to $834.1 billion in 2034.
Embedded finance delivers financial services through a non-financial platform. Embedded financial solutions have several use cases, including:
- embedded lending
- digital banking
- embedded payments
- buy now, pay later (BNPL)
- insurance
- credit cards
Banking as a Service (BaaS) providers power these embedded financial services through the use of Application Programming Interfaces, or APIs.
Everyday consumers have become quite familiar with embedded finance solutions. For example, companies like Klarna offer BNPL solutions that are now commonplace during checkout at many major retailers. Other companies like Amazon and Shopify have also implemented solutions like Stripe for payment processing.
However, it’s embedded lending that’s garnering attention these days. In the near term, the embedded lending market is expected to exceed $30 billion in annual revenue.
BaaS platforms allow lenders using embedded financing to retain control of credit, compliance, and risk management, while fintech companies and software as service (SaaS) platforms influence customer acquisition and the user experience.
Embedded lending provides financial institutions with an opportunity to modernize their business models and "plug in” to platforms their customers already trust without needing to design tools from scratch or spend money on marketing for leads. Your bank can also benefit by expanding its lending capabilities, decreasing acquisition costs, and building a scalable, recurring revenue stream.
Core Architecture of Lending APIs
APIs make embedded lending work behind the scenes. APIs are simply channels that connect your bank’s software system to a partner’s platform.
These channels allow small business users to apply for and access loans from the apps they’re working in, like point-of-sale or accounting platforms. They don’t even have to visit your bank’s website at that point unless they choose to.
This “plug-and-play” approach enables your bank to retain control of the loan process while offering services to more customers through trusted third-party Fintech platforms.
The following are the key elements of a standard embedded lending API system:
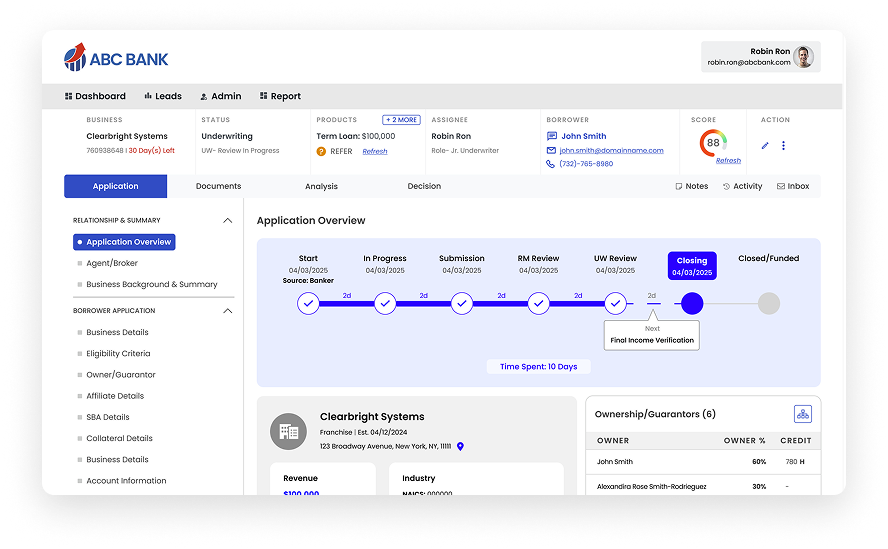
- Application Intake: The platform collects loan application data from the small business user, and then the data is transmitted through the API to your bank's system in real time.
- Pre-Qualification: The API confirms basic eligibility by rules you specify (e.g., business age, revenue, credit rating). The system then determines whether the user will be approved before it sends a full application.
- Credit Decisioning: Your financial institution factors in applicant data during the underwriting process. Then, an approval or rejection is returned via the API in real-time or within a defined period.
- Loan Disbursement: Money is sent to the borrower’s account once approved. This can take place quickly, at times on the same day.
- Servicing and Repayment Tracking: The API keeps the platform (and your staff) updated with repayment status, balance, and due dates. Borrowers can directly check loan details from the platform.
At various touchpoints, your bank’s system will connect to the API platform. These touchpoints include the Know Your Customer (KYC) process for customer identity verification and uploading and sharing of documents. From there, all parties will receive status and notice updates to ensure a fast, secure, and easy lending process.
This seamless setup makes it possible to increase your services to more SMBs without taking on more risk.
Compliance and Risk Management Layering
An effective and successful embedded lending program depends on many factors, including speed and a great customer experience. But strong compliance and risk controls are also essential. As a regulated entity, your bank is responsible for ensuring all activity meets federal and state banking regulations.
The Bank's Role in Compliance
Banks that implement BaaS and embedded lending must ensure that all lending activity is compliant with guidelines released by the FDIC, OCC, and state banking regulators. These encompass Know Your Customer (KYC) and Anti-Money Laundering (AML) screenings that identify applicants and help avert fraud and criminal activity.
Your systems should also be designed to meet fair lending laws like the Equal Credit Opportunity Act (ECOA), which ensures that all borrowers are treated equally well regardless of their race, gender, or background.
How to Stay in Control
Maintaining control starts with using your own underwriting models to analyze each applicant. You can also use compliance-as-a-service providers or create your own tools to filter for risk, fraud, and regulatory issues. Make sure the API logs all activities and decisions with full audit trails. Real-time monitoring identifies issues before they become problems.
Data Security
Security must be incorporated from the outset. This means strong encryption, tokenization, and secure API gateways to protect sensitive customer data, ensuring your bank is compliant with data privacy laws. It can also help your financial institution build trust by prioritizing the security of borrower data.
Partner Onboarding & Integration Considerations
Partnering with third-party platforms for your bank’s embedded lending program involves more than adding lines of code. A strategic approach for partner selection, technical integration, and legal alignment is key to long-term growth and success.
Finding the Right Platforms
The first step is evaluating and selecting embedded finance providers that currently support small business customers. Choose platforms that have an active user base that can naturally support a lending platform, such as accounting software, invoicing systems, e-commerce websites, or point-of-sale systems.
The best partners are those whose users often engage in cash flow management or financing applications. Also, consider the embedded finance platform's ability to provide seamless integration with your systems, both operationally and technically. They should have a development team, support staff, and be willing to work closely with your bank during the onboarding process.
Technical Onboarding Steps
Once a partner is selected, offer a sandbox environment where team members can test the lending flow before going live. Keep technical documentation straightforward, with example code and software development kits (SDKs), to speed the integration.
Staying current with new API versions is important, too. Discuss API updates from your system and ensure your partner is able to facilitate an open connection with the right processes when there’s a new version of an API.
Make sure your partner knows how to handle updates without breaking the connection. Uptime and stability are important. Agree on service level agreements for system availability and support response times.
Legal and Operational Alignment
A good foundation that lays out the legal and operational responsibilities of each stakeholder can build trust and avoid confusion down the line.
Pre-launch, all parties should have clear agreements that outline what is to be done by whom. That is, who does which part of the customer journey, who keeps what information, and how issues will be resolved.
Set up data-sharing agreements that detail how customer information is used, stored, and protected. Set up mutual service expectations, such as how quickly customer service teams need to respond and how loan approvals will be communicated.
Underwriting Logic and Capital Deployment
Ensuring that embedded lending works for your bank will, in part, depend on how well it manages risk, capital deployment, and underwriting control.
Your Bank’s Role in the Embedded Lending Underwriting Process
Maintaining command of the underwriting process is essential to managing credit risk effectively. With your bank backing the embedded lending platform, you should stay in control of the credit decisioning process, regardless of where the application is initiated.
To achieve this, your bank will need to impose its own credit policies, lending criteria, and regulatory screening to ensure prudent decision-making.
By utilizing historical credit performance data and external sources such as alternative data, your financial institution can create adaptive underwriting models that more precisely measure creditworthiness.
Experiment with segmenting candidates based on such variables as risk profile, loan type, or industry vertical. Tiered loan offers, tailored to each candidate's risk grade, can minimize default risk.
Benefits of API-Based Underwriting
API-based underwriting facilitates quicker loan decisions and conveniently delivers them across the platforms your small business customers are using. Because API underwriting streamlines the loan process and delivers a more tailored experience that meets customer needs, it leads to higher customer engagement, which often leads to long-term customer loyalty and retention.
Automation significantly decreases manual processing time, and all applications are considered with the same criteria. This makes for better risk management and allows your bank to scale embedded lending with many partners without adding operational complexity.
Monetization Opportunities for Banks
Embedded lending enables banks to develop new revenue streams by monetizing the loan product as well as the infrastructure behind it.
Transaction-based Fees
The most straightforward way to monetize embedded lending is by charging transaction fees to platform partners. Each time a loan is processed or disbursed through the API, your bank can charge a fee for providing the service, thereby creating recurring revenue tied to volume.
Interest Income
Interest income is a core driver of profitability for banks. By deploying your bank’s own capital through embedded lending, your bank receives interest in the same way as traditional lending.
The key difference is that your financial institution can maximize its efficiency through less effort in acquiring loans, meaning reduced customer acquisition expenses, but at increased scalability through more loan volume.
Tiered-Pricing
Tiered pricing models can provide great returns. You can assess fees or interest rates that vary by loan volume, partner size, or risk levels of the borrowers. This model allows you to appropriately compensate high-performing platforms while, at the same time, adequately compensating your bank for higher risk loans or those with additional servicing complexity.
Overcoming Implementation Challenges on Embedded Lending Platforms
Implementing an embedded lending program has a few pain points and challenges. But with a little preparation, roadblocks can be overcome.
When introducing new technology into a well-established banking environment, resistance is common. Start small by piloting your embedding lending strategy with one or two well-established platforms.
A successful pilot does more than prove it works for your bank: it establishes internal confidence among stakeholders and lays the groundwork for a broader roll-out.
Internal compliance and risk also provide hurdles. Because your bank is still responsible for all regulatory compliance, it’s necessary to engage your compliance and legal team early in the planning stages. This will help to identify potential issues sooner, before the actual launch, and promote an environment where compliance and risk are a priority from day one.
APIs can be complex, especially if your internal systems don’t support real-time integration. To bypass this challenge, consider working with third-party partners or BaaS providers who specialize in delivering and managing secure, compliant APIs.
Conclusion
While there are many opportunities across the broader embedded finance ecosystem, bank and financial service providers can satisfy their customers' growing demand for small business lending in a digital-first world.
Embedded lending, powered by robust APIs and serviced on trusted platforms, offers a scalable, low-cost way for banks to grow their lending portfolios while staying compliant, secure, and in control. With the proper partnerships and infrastructure, your bank can provide easy access to credit right in the software applications SMBs use.
The opportunity is clear: embedded lending isn't simply a tech stack upgrade; it's a growth strategy. Leverage it now to stay ahead of your competitors, deepen partner relationships, and drive consistent revenue.
Ready to See What Embedded Lending Can Do For Your Bank?
Unlock new revenue streams and scale your small business lending program with Biz2X's plug-and-play API solutions. Learn how your bank can lead the digital shift in business lending by requesting a demo.
FAQs
1. What does embedded lending offers that traditional banking cannot?
Embedded lending can extend your bank’s reach well beyond what a physical bank branch or even digital banking can offer. By embedding commercial loan opportunities in applications that startups and small business owners are using, every point of engagement counts, often leading to a higher law of average success than traditional lending.
2. Are there non-financial companies that already offer embedded lending to business owners?
Yes. For example, Shopify offers merchant cash advances to its merchants while Amazon offers lines of credit and term loans directly through its platform. Meanwhile, Stripe offers working capital loans to businesses that use its services. Even Uber offers its drivers cash advances based on their revenue.
3. How can banks keep up with regulatory requirements while offering embedded lending through third-party websites?
Lenders need to ensure that API systems are designed to incorporate compliance checks, such as KYC and AML, directly into the lending process, e.g., customer identity verification, documentation, and audit trails for all decisions.
4. What types of data are used during the underwriting process for decision-making in embedded lending?
In addition to traditional credit scoring models, it looks at alternative data such as transactions from credit and debit cards, bank accounts, and business accounts. It also evaluates data from customer behavior on the platform and suspicious activity that might signal fraud. Finally, embedded lending platforms factor in cash flow data, annual revenue, and time in business.
5. What factors should banks think about when evaluating a third-party platform partner?
Banks should look for partners that have strong experience in providing embedded lending services to small business owners. Platforms should also have the technical capabilities for solid API integration. They should also be open to outlining clear legal, operational, and data-sharing responsibilities in an agreement.
What’s happening
See the latest from Biz2X.
What Is Credit Union Account Opening Software? A Complete Guide
A credit union is formed and maintained by its members. Opening a new account is often the first step of becoming a prospective member. However, if the process feels slow and requires frequent document uploads, branch visits, or more, there
Open a Business Checking Account Online: Requirements and Eligibility
A business checking account is essential for managing daily finances, separating business expenses from personal expenses, and maintaining accurate records for tax filing and compliance. Banks also understand the various requirements of sma
What Is Open Banking? Benefits, Risks & Working Explained
The world is evolving digitally, and industries are competing to provide digital experiences faster. In return, consumer behavior is also evolving accordingly. With personalization and multiple online payment options, the way transactions t
How Mortgage Loan Origination Software Is Transforming Digital Lending in 2026
Mortgage loan origination software (LOS) is quite useful for modern lenders, banks, and credit unions. It helps them streamline the origination of workflows, including application, document collection, underwriting, approval, and more. With
12 Loan Management Software Capabilities That Matter Most in 2026
Managing loan lifecycle, the traditional way required banks and lenders to invest heavily in manual resources. The process was slow, which led to low efficiency, more inaccuracy, and high turnaround times. Then loan management software came
How to Secure an Instant Small Business Loan for Urgent Business Expenses
Instant small business loans are supposed to provide faster access to funding than traditional financing options. However, the speed of funding may not be as fast as the loan providers may claim. Lenders often need to conduct thorough analy
Best Small Business Loans for Startups: A Complete Guide to Funding Your New Venture in 2026
Startups and small businesses often need to deal with immediate operational expenses. As their business plan is new, and they’re often figuring out things like logistics and suppliers, their cost expectations can surge. Without any means of
Top Benefits of Using Loan Management Software for Small Businesses in 2026
Loan management has evolved far beyond what you can imagine. Earlier, compliance was less strict, and everything was managed manually. This often led to a lengthier loan origination process and also left the workflows susceptible to fraud.
Small Business Loans for Startups: What to Consider Before Borrowing
Small business loans for startups can be quite helpful in the early stages of your business. According to Digit, 38% of startups fail because of poor cash flow. When this happens, owners cannot arrange working capital for daily operations l
A Complete Guide to Mortgage Lending Software for Modern Lenders
Modern banks and lenders are upgrading their lending technology to offer more convenience and simplify routine operations. Mortgage lending software provides all this while increasing productivity, lowering operational costs, and eliminatin
How to Choose the Right Credit Management Software for Your Business
Credit management software plays an important role for banks. They help them evaluate borrower risk, credit profile, loan portfolios, and compliance. Now with AI-enabled functionalities, these automate loan origination and underwriting as w
How Enterprise Risk Management Software Enables Proactive Risk Identification
Facing challenges, risks, and uncertainty is part of running a business. However, these challenges become unfair when their source of origination is fraudsters or others with malicious intent instead of market competition. To help businesse
How Enterprise Risk Software Helps Identify Emerging Threats and Manage Risks
Today, businesses and organizations must deal with various risks, ranging from cyber security threats, regulatory changes, and supply chain disruptions to financial uncertainties and operational challenges. Mitigating these challenges proac
Why Financial Institutions Are Investing in Advanced Risk and Compliance Tools?
There are several types of risks that banks face in their daily operations. From data theft to literal financial frauds, a single mistake can leave the bank vulnerable to so much damage. On top of it, they may need to face a heavy lawsuit f
The Role of an Account Origination Platform in Digital Banking
Today’s highly competitive digital-banking environment keeps banks on the edge. They are expected to deliver a seamless experience to customers and meet their expectations in terms of speed and comfort. To provide a better onboarding experi
How Online Account Opening Software for Banks Improves Customer Onboarding
Banking technology does more than fortifying your banking operations. With both online and mobile banking applications available easily, your technology becomes the customer’s first meaningful interaction. Apart from this, the solution shou
What Is Loan Business Software and Why Does Your Lending Business Need It?
Loan businesses, including banks, credit unions, non-banking financial institutions and digital lending platforms often handle many applications, documents, payments, and customer interactions. Managing this manually is quite time consuming
The Ultimate Guide to Account Opening Software for Banks
Today, users expect banks to offer them state-of-the-art experience in all bank-related services. To begin with, even simple processes like opening a bank account or seeing a bank statement should be amazingly fast. This can be achieved by
How to Optimize Your Bank Account? Business Strategies for Startup Growth in 2026
Choosing the right bank account for business is one of the primary and early financial decisions that you need to make. This account will keep all your business expenses separate from personal expenses and help with tracking and monitoring
How Small Businesses Can Apply for Business Account Online Easily
Applying for a business account online has become quite simple today. With different banks opting for digital transformation, you can fill and submit an application form for different types of bank accounts online. The process is faster, mo
How to Open a Business Bank Account and Set Your Business Up for Growth
Preparing for growth means more than strategic business planning. You should make sure that your financial ecosystem is strong and capable of handling a growing number of transactions, while providing competitive interest rates and other pe
How to Open a Business Bank Account Online and Simplify Business Finances
Selecting the right banking partner is one of the first steps in proactively managing your business expenses. Today, it has become easier to open a business bank account. In fact, you can apply online in a few minutes, but applying with the
How to Choose the Best Project Portfolio Management Software for Your Business
Project Portfolio Management (PPM) software is dedicated to helping organizations select, prioritize, and monitor projects to match company goals. These help cover the gap between strategy and daily execution. Instead of focusing on individ
How to Open Business Account Online: A Step-by-Step Guide
Opening a business account online is the first steps towards managing your funds safely and efficiently. With different perks that various banks offer, you can open online bank account for different purposes. While one account can be for ma
The Business Benefits of a Modern Credit Origination System
There’s a fundamental shift in the lending industry. The way people and businesses used to borrow money has changed. Earlier, only banks used to be reliable options, but today several non-banking financial institutions have also emerged inc
Top 15 Loan Origination Features Every Modern Lender Should Have
In the first two decades of the 21st century, lenders still relied on traditional loan processing, which lead to longer loan processing, decision making, and lengthy paperwork. While the method worked, it is not exactly fine-tuned for the r
How to Evaluate and Choose the Best Consumer Loan Origination Software
Lenders interest in consumer loan origination software often face struggle in choosing the right solution. They see a few development approaches in front of them, with each having its own merits and demerits. While consulting a tech firm he
Key Features of a Modern Commercial Loan Origination System
A commercial loan origination management system (LOS) is a dedicated software solution designed to help financial institutions manage the entire lifecycle for a loan. It is developed in collaboration with loan experts to handle all stages o
How Embedded Lending Can Help Cover Cash Flow Gaps
Disclaimer: All articles and all information in the Knowledge Center are provided for general informational purposes only, and do not constitute financial, tax, legal, accounting or other professional advice, and may not be relied on for an
How to Write a Lender-Ready Plan for Your SBA Startup Loan Application
Obtaining an SBA startup loan needs a well-planned, risk-mitigating and financially secure business plan. Regional banks are now more stringent regarding providing loans to new ventures as the post-inflationary market in 2026 restricts lend
How AI is Powering Quick Small Business Loans at Local Banks
The landscape for community banking is going through a substantial shift as AI accelerates how rapidly small businesses can access quick small business loans from their community banks and local entrepreneurs. Traditionally, regional banks
How to Apply for Small Business Loan Funding via Regional Banks
When you want to grow your business, manage seasonal fluctuations, or invest in long-term assets, apply for small business loan is a critical part of the plan you create to achieve these objectives. While many entrepreneurs default to using
How Digital Onboarding is Revolutionizing the Small Business SBA Application Process
The small business SBA ecosystem has experienced the largest change since the start of the U.S. Small Business Administration in 1953. Historically, applying for a small-business loan through a federal agency has been quite complex for entr
Paying SBA Loan Debt Early: Pros and Cons of Prepayment
Making the right decisions about paying SBA loan will directly impact the company's current and future growth. This should be considered a top-level strategic decision for small business owners. The desire to become "debt-free" for many sma
5 Key Documents Required for Small Business Loans for Starting a Business
The process of securing small business loans for starting a business is complicated and requires both a systematic approach and extremely careful documentation. Due to the restrictions placed on capital by the regional banking system and th
Understanding the SBA Business Loan Process: A Step-by-Step Guide
SBA business financing is an effective way for small business owners to access lower-cost financing to support the creation of sustainable growth and long-term value in their businesses. Banks and other lenders partner with the SBA in offer
Why Fast Funding is Essential for Small Business Loans for Business
For many vibrant entrepreneurial manufacturers, accessing small business loans for business can be time-sensitive due to the need to obtain liquidity quickly to grow. When a manufacturer finds a market gap, there may not be enough time for
How Collateral Affects Small Business Loans for Startup Companies
Obtaining small business loans for startup companies is crucial to achieving the milestone of launching an emerging business and scaling its operations. However, one of the biggest roadblocks for many entrepreneurs is proving to financial i
Top 7 Best Loan Management Software for Indian NBFCs in 2026
Choosing the best loan management software is critical both to improving operational efficiency and to managing a growing loan portfolio. NBFCs will offer many different types of loans, including consumer lending, small and medium enterpris
Why the SBA Loan is the Best Choice for Working Capital
An SBA loan has become an increasingly important solution for companies that are looking to increase the level of liquidity they maintain to compete in today's fast-paced business world. Today's modern finance ecosystems are placing increas
Funding the Future: SBA Programs for Green B2B Energy Initiatives
The SBA small business administration is on the verge of becoming a major financing source for the transition of the native American economy toward more sustainable energy practices. Sustainability is no longer seen as merely a compliance o
Navigating Risk: The Safest Business Loan for a Startup Company Success
Imagine you're at the helm of a promising startup, staring down high-stakes decisions with limited runway. As a business leader, you've bootstrapped your way this far, but scaling demands capital, fast, secure, and sustainable. What if the
The 2026 Power List: Best Lenders for Small Business Loans
The best lenders for small business loans in 2026 will transform how entrepreneurs raise capital through innovative lending solutions. The advances in technology have impacted service delivery for small business owners due to the rise of di
The Melting Pot Still Works. The Playbook Doesn’t.
What the World Cup and America’s 250th Tell Us About the Next Chapter of American Enterprise. By Rohit Arora, CEO & Co-founder of Biz2Credit Welcome to the Arora Analysis. Every month, we'll dive back into trending topics and financial moni
Embedded Finance Explained: How Your Brand Can Become a Financial Powerhouse
The concept of embedded finance explained has gained significant momentum and can no longer simply be labelled as a trend. Rather, it is an overall transformation of the way in which businesses will grow, monetise, and retain customers. Wit
Comparing Top Rated Small Business Loans: Fixed vs. Variable Rates
Loans for small businesses are important for both small business owners and regional banks as they assess the Federal Reserve's impact on interest rates for 2026 and beyond. Because of these changes to borrowing costs by the Federal Reserve
Bank Small Business Loan Review 2026: Is It Right for You?
The KeyBank small business loan portfolio in 2026 is still a leading source of funding for mid-sized businesses. As the business credit markets continue to change, identifying how KeyBank structures its lending will aid regional banks in as
Ways Embedded Finance Can Reduce Abandoned Applications
Key Takeaways Friction is the Primary Killer of Conversions: Small business owners rarely abandon loan applications due to a sudden lack of interest; instead, they drop out because of excessive manual data entry, rigid document requests, an
AI-Powered Verification: The Future of Consumer Loan Origination Systems
Financial institutions have witnessed a radical shift in how they approve consumer loans with the introduction of consumer loan origination systems (LOS). In just three years, AI-powered verification methods are setting new standards for sp
The Evolution of Consumer Loan Origination Systems in 2026
In 2026, the lending environment has undergone a radical transformation. There have been so many changes regarding the way digital technology is used, an increased number of compliance regulations, and revised borrower demands that have dra
Why Choosing the Right Embedded Finance Providers is Your Biggest 2026 Growth
Business leaders, imagine transforming your core platform from a simple service into a revenue-generating powerhouse that seamlessly offers financial services right where your customers already spend their time. In 2026, as competition inte
How Embedded Finance Products are Transforming Supply Chains
As a business leader navigating the complexities of modern supply chains, you know the drill: delays in payments, cash flow crunches, and fragmented financial services can derail even the most efficient operations. Imagine a world where fin
Unpacking Embedded Finance Meaning in the Era of Agentic AI
Imagine you're a business leader navigating the fintech landscape, where every customer interaction could unlock new revenue streams. But traditional banking holds you back with clunky integrations and slow approvals. What if financial serv
Embedded Financial Services: The Secret to Slashing B2B Sales Cycles
Business leaders, what if you could cut your B2B sales cycles from months to days, closing deals faster while delighting clients with instant value? In today's high-stakes market, are you still relying on clunky traditional banking processe
How AI is Reshaping the Embedded Finance Market Dynamics
Companies that think beyond their industry and scope of work often outperform their competitors in the long run, a lesson many traditional financial institutions and traditional banking sectors are now learning, especially concerning embedd
SBA Express Lenders vs. Fintech: Comparing Speed and Guarantee Fees
SBA express lenders are receiving new attention from borrowers as banks are being challenged to compete with fintech based on speed and cost. With challenges from market competition, lenders are also under pressure to deliver quicker approv
Eye on the Prize in the Age of AI
By Rohit Arora, CEO & Co-founder of Biz2X Last week, against the historic backdrop of the New York Stock Exchange trading floor, Biz2X hosted an intimate roundtable dinner—the first in our quarterly "Frontiers in Funding" dinner series. We
How the 2026 SBA Disaster Loan Rule Speeds Up Business Recovery
Business leaders, imagine a hurricane or flood devastates your operations in a declared disaster area, leaving your small business scrambling for funds amid bureaucratic red tape. What if a single rule change could slash recovery timelines
Expanding the Reach of Traditional Lending Technology for Banks
USA regional and small banks are experts in their market when it comes to lending to businesses. Local small businesses receive funding from these banks on a daily basis. But outside competition is significant. Fintech companies have create
Why Smart Underwriting Solutions are the Key to 2026 Revenue
Regional and community banks are competing with significantly more fintech lenders, as well as larger financial institutions. This competition is primarily due to larger financial institutions utilizing digital technology for their lending
Digital Onboarding: The Critical First Step in Lending Process Digitization
Imagine a scenario where your most promising prospective client walks through your virtual front door, ready to engage with your financial services, only to be met with a labyrinth of static PDF forms and a request to mail in physical copie
The Gold Standard for Secure Lending Technology Solutions
Lenders work with very sensitive data. They handle personal details like Social Security numbers, bank account information, credit scores, and income data. A single data security or compliance breach can lead to significant fines and reputa
The Security Architecture of Modern Cloud-Based Loan Management Systems
Picture a fintech executive dealing with increased amounts of loans and cybersecurity threats around every online turn. How can you make certain that your cloud-based loan management systems help protect your borrowers' sensitive data while
Using AI-Driven Credit Assessment to Forecast Delinquency
As a business leader in lending or financial services, you've felt the sting of unexpected delinquencies derailing your forecasts and profitability. What if you could peer into the future of borrower repayment with precision, turning risk i
Healthcare Finance: Innovative Embedded Lending Examples at the Point of Care
Are you, as a healthcare CEO or fintech leader, watching patients walk out the door because upfront costs prevent them from receiving critical treatments? Imagine flipping that script: seamless financing right at the point of care, boosting
Why Automated Loan Solutions for Lenders Are Essential
In an era where market agility defines the line between growth and stagnation, the traditional banking model is facing a silent revolution. For executive leaders at modern financial institutions, the question is no longer whether to embrace
Hyper-Automation: The New Standard for Loan Workflow Automation
In the fast-paced world of modern finance, the traditional hurdles of manual document management and fragmented communication are no longer just inconveniences, but they are liabilities. For business leaders, the challenge is clear: how do
Scaling Beyond Borders: International Loan Lifecycle Management for US Firms
Global megabanks are taking part in the current international expansion of loan lifecycle management. Regional banks, community banks, credit unions, and specialised lenders across the United States are also actively supporting their borrow
Enhancing Investor Transparency through Loan Tracking Management Software
In the high-stakes financial landscape of 2026, the relationship between financial institutions and their investors has shifted from passive reporting to active, real-time engagement. Institutional investors, private lenders, and credit uni
The Future of Commercial Credit: Trends in End-to-End Lending Automation
For today’s commercial banking leaders, the "speed of business" is no longer just a boardroom cliché, but a survival metric. Imagine a world where a complex commercial credit request doesn't languish in an underwriter's inbox for weeks but
Real-Time Testing: AI-Powered Risk Assessment for 2026 Volatility
Think back to the last time a market shift caught your organization off guard. Perhaps it was a sudden supply chain disruption or an overnight change in regulatory requirements that left your compliance team scrambling. For most business le
Automated Loan Decisioning for Small Business: High-Touch Speed, Low-Cost Risk
Picture this: A small business owner submits a loan application at 9 AM, and by noon, they have funding to seize a market opportunity, without endless paperwork or waiting games. As a lending executive, are you still relying on manual proce
How Can Embedded Lenders Stay Competitive? Here are Some Steps
Key Takeaways Market data has shown that the market for embedded small business lending platforms has grown exponentially in the now digital first economy, and the landscape for embedded lenders has become more competitive. Embedded small b
Integrated GRC Software: A New Standard for Decisioning & Risk Monitoring
In the business space today, organisations are facing a myriad of challenges that can impact their operations, reputation, and financial stability. Governance, Risk, and Compliance (GRC) is a structure that organisations are turning to for
Why Vertical SaaS Providers are Prioritizing Embedded Lending Technology
Software platforms are seeing a boom in usage at the moment. Vertical SaaS companies are functioning as the operational control centres for many industries. These are helping industries such as healthcare scheduling systems, construction ma
Predictive Modeling: Using Advanced Loan Portfolio Analytics to Forecast Risk
To lead a financial institution in 2026 is to navigate a landscape defined by rapid volatility and digital acceleration. For C-suite executives and credit heads at banks, NBFCs, and credit unions, the “rear-view mirror” approach to loan por
Why Digital Loan Origination is the Secret to Faster Small Business Growth
You're a small business owner whose cash flow is strangled by slow loan approvals, or a lender watching competitors snag deals because their processes move at glacial speeds. Does this sound familiar? As a business leader in fintech or bank
Commercial Lending Technology: Transforming the Mid-Market Experience
Mid-market companies are considered one of the most underserved segments in the United States economy. These businesses are growing larger and more complex every day than small businesses. These companies are still lacking basic access to e
The Ethics of AI: A New Pillar for Risk Management in Banking
Banks and financial institutions in the banking industry are eager to adopt AI technology across multiple areas of their banking operations, like credit risk modeling, cybersecurity, and managing liquidity risk/ market risk. It will help by
Scaling Without Headcount: The ROI of Loan Automation Software in 2026
You're a lending executive staring at a ballooning loan portfolio, but your team is maxed out on manual underwriting and paperwork. What if you could double loan approvals, cut processing times, and boost ROI, all without more hirings? In 2
Open Banking Loan Solutions: Achieving Real-Time Cash Flow Visibility
The United States is experiencing a surge in the acceptance of open banking. Financial institutions have started delivering their financial services to many small business clients with the help of open banking loan solutions. This whole mov
The Rise of Digital Onboarding: Transforming UX with Lending Technology
As business leaders, you can drastically reduce onboarding times from days to minutes and attract thousands of new borrowers to your lending platform while traditional banking institutions frantically look for ways to do the same thing. Are
Beyond FICO: Using Alternative Data in AI-Based Lending to Reach Thin-File
As a business leader in financial services, you're eyeing untapped markets where millions of thin-file borrowers, small business owners with solid cash flows but scant credit history, slip through traditional FICO cracks, leaving billions i
Self-Service Lending: Empowering Clients with Borrower Onboarding Solutions
You're a lending executive at a mid-sized credit union, watching new borrowers abandon loan applications midway due to slow onboarding. What if they could self-serve, uploading docs via mobile, tracking progress on dashboards, and getting r
Automating Compliance: The Regulatory Edge of a Credit Risk Mitigation Platform
As an executive in financial services, you are no doubt familiar with how difficult it can be to keep up with constantly changing regulations that impact your business. If you spend late nights reviewing financial statements or have teams r
From Payments to Credit: The Evolution of Embedded Lending Platforms
Imagine you're a business leader navigating a market where customers expect instant everything, from checkout to fulfilment. What if your platform could not only process payments but also approve loans in seconds, turning one-time buyers in
Predictive Liquidity: The Future of Lending for US Mid-Market Firms
Imagine you're a mid-market CEO in the US, facing a cash-flow crunch just as a prime opportunity arises from expansion into new markets or the acquisition of a distressed competitor. Do you scramble for traditional loans, waiting weeks for
Scaling Private Credit with Advanced Loan Process Automation
Picture yourself as a private debt investment fund manager with access to a steady stream of high-quality lending opportunities. Unfortunately, your team has become bogged down by excessive repetitive data-entry tasks, manual loan underwrit
Reducing Total Cost of Ownership (TCO) with Cloud-Based Lending Software
Besides interest margins, regional banks and credit unions in the USA charge some extra fees on every loan. These fees raise the total cost of ownership (TCO) and make lending operations less profitable, even with increased loan volumes. In
Biz2X Frontiers 2026 2026: Five Forces Re-Architecting Finance, AI, and Small Business Lending
The global financial system is entering a decisive new chapter. At Biz2X Frontiers 2026 international leaders from banking, fintech, private credit, capital markets, technology, and public policy came together to examine what’s next, and wh
Next-Gen AI-Powered Lending Solutions: Hyper-Personalization
In today’s cutthroat financial environment, executives have witnessed the most critical shift: the transition from traditional lending to hyper-personalized lending. Today, the key to success and the differentiator that will tip the scales
The Borrower Experience Upgrade: How a Loan Portfolio Platform Boosts Customer Satisfaction
In an era where customer expectations are shaped by seamless digital interactions in every other industry, the lending process often lags, characterized by complexity, delays, and a lack of transparency. The resulting friction in the borrow
Working Capital Business Loan Solutions: Beat Cash Flow Gaps
For small business executives, managing the tension between seasonal revenue fluctuations and fixed operational obligations is a critical leadership challenge. When outstanding receivables coincide with immediate liabilities, such as payrol
Future-Proofing Your Funds: The Cloud Security Advantage of Modern Loan Solutions
As a business leader in financial services, you're staring down a surge in small business loan applications amid economic volatility, but legacy systems are buckling under cyber threats and manual workflows. What if you could slash loan ori
The US Small Business Guide to Loans: Why Your Lender Needs Modern Lending Software
You're a lender at a credit union or community bank, staring down a stack of small business loan applications. Deadlines loom, borrowers wait weeks for decisions, and your team drowns in manual paperwork, costing you deals to faster fintech
Future-Proofing the Supply Chain with a Dynamic Risk Management System
You're steering your organization through volatile markets, supply chain hiccups, and cyber threats, yet instead of dodging opportunities, you're seizing them. Sound familiar? As a leader in business finance or digital lending, you know ris
The AI Risk Manager: How Banks Are Governing AI Models to Maintain Trust
Your team deploys a cutting-edge AI agent for fraud detection, only for a biased algorithm to flag legitimate transactions, sparking regulatory scrutiny and customer backlash. As AI adoption in banks surges, how do you harness it without er
Scaling Secrets: Leaders Leveraging Alt-Lenders in the Commercial Loan System
Imagine you're at the helm of a growing enterprise, staring down a cash flow crunch that traditional banks can't lend fast enough. You've built your business from the ground up, but scaling demands capital now. What if you could tap into a
End-to-End Excellence: Streamlining the Loan Lifecycle with Integrated Loan Tracking Management
In 2026, the margin for error in commercial lending has almost moved to null. As an executive, your day is a high-stakes balancing act, which includes answering borrower inquiries, handling loan disbursements, and dealing with portfolio ris
Growth Capital for the Everyday Business: Unlocking Small-Dollar Loans Under the SBA Loan System
Imagine you're a business leader navigating tight cash flow, eyeing that next expansion, but traditional bank loans feel out of reach. What if the SBA Loan System held the key to small-dollar loans that fuel everyday growth without the red